Last week an old friend of mine, an architect, sent me the Crain’s story about Manhattan office rents. There was no hello, just the link and a note that said, “Tell them about the elevator.” She signed a ten-year lease in 2022 without ever thinking to vet the landlord, and she’d like you to know how that turned out. Her hope, and mine, is that you’ll vet your landlord before you sign anything.
The piece opens on the good news, and there’s plenty of it. The city’s biggest office landlord bought 245 Park Avenue, just north of Grand Central, out of bankruptcy four years ago, and the tower is now 100% leased and getting a golf lounge. Across that landlord’s buildings, new tenants are paying 16% more than the ones they replaced.
Then it gets to the mortgages. Almost every office tower in Manhattan carries a big one, and owners who have to refinance are looking at about double their old rate. A Wall Street firm figures the extra interest will eat nearly all of that new rent. It’s simple math, since rents climb one lease at a time and interest jumps the day a loan resets.
I’ve been representing tenants since 2004, and when a landlord comes up short, he almost always takes it out of the building, one skipped repair at a time. In her building, the repair he skipped was the elevator, and she spent eleven weeks climbing nine flights of stairs to her own office. I’ll get to that, but her story starts two years earlier, with a set of windows.
She Fell for the Windows
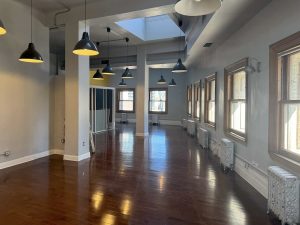
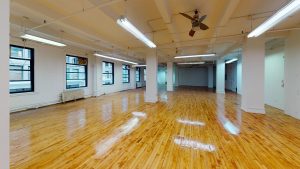
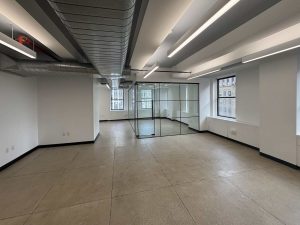
She found those windows in the spring of 2022, on the tenth floor of an old Murray Hill loft. The ceilings were twelve feet high, there was glass on three sides, and by ten in the morning the whole corner was full of light.
Her firm had fourteen people crammed into a sublet that was about to run out, so she was looking hard. She told me later she knew this was the one before the leasing agent finished turning on the lights. Now she laughs about it, because she’s spent twenty years telling her own clients to look past the finishes and check the bones.
She didn’t call me, either, and I still give her a hard time about that. She figured the landlord’s agent could handle a deal that size, and he was friendly and full of reassurances. Within a few weeks they’d agreed on ten years for 5,000 square feet, with eight months of free rent.
The Due Diligence Only Went One Way
Then came the landlord’s review of her firm, which was thorough and, to be fair, entirely standard.
They asked for two years of tax returns, six months of bank statements, a letter from her accountant and a reference from her last landlord. And because the firm was small, they also asked for her personal good guy guarantee.
She sent every page within a week, which is what you do when you want the space.
The irony, though, is that she knew better. When she bought her Upper West Side co-op, her lawyer spent a week on the building’s financials and its mortgage. That’s how buying into a building works in this city. Yet on a ten-year office lease worth nearly $3 million, no one on her side asked a single question about the landlord’s mortgage, including her.
Then the Fed Came Calling
If anyone had looked, they’d have seen the owner’s 2019 floating-rate loan from a debt fund. Debt funds are the lenders you go to when the banks say no, and they charge for it. A floating rate means your payment goes up when interest rates do.
She moved in that October, right in the middle of the fastest run of rate hikes in forty years. Once the owner’s rate cap ran out, every one of those hikes landed on his interest bill like a piano falling out of a window.
She didn’t know any of that yet. She just knew the second half of her $300,000 build-out allowance was due when construction wrapped, and it didn’t show. The agent said it was in processing. It processed for four months, and she paid her contractor out of the firm’s credit line while she waited.
Eleven Weeks of Stairs
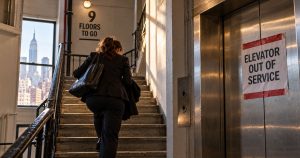
Over the next year, the building got a little worse every month. The lobby renovation from the leasing brochure never started, though the drawing of it sat on an easel by the mailroom until the sun bleached it. The cleaning crew went from five nights a week to three, and the property manager changed twice.
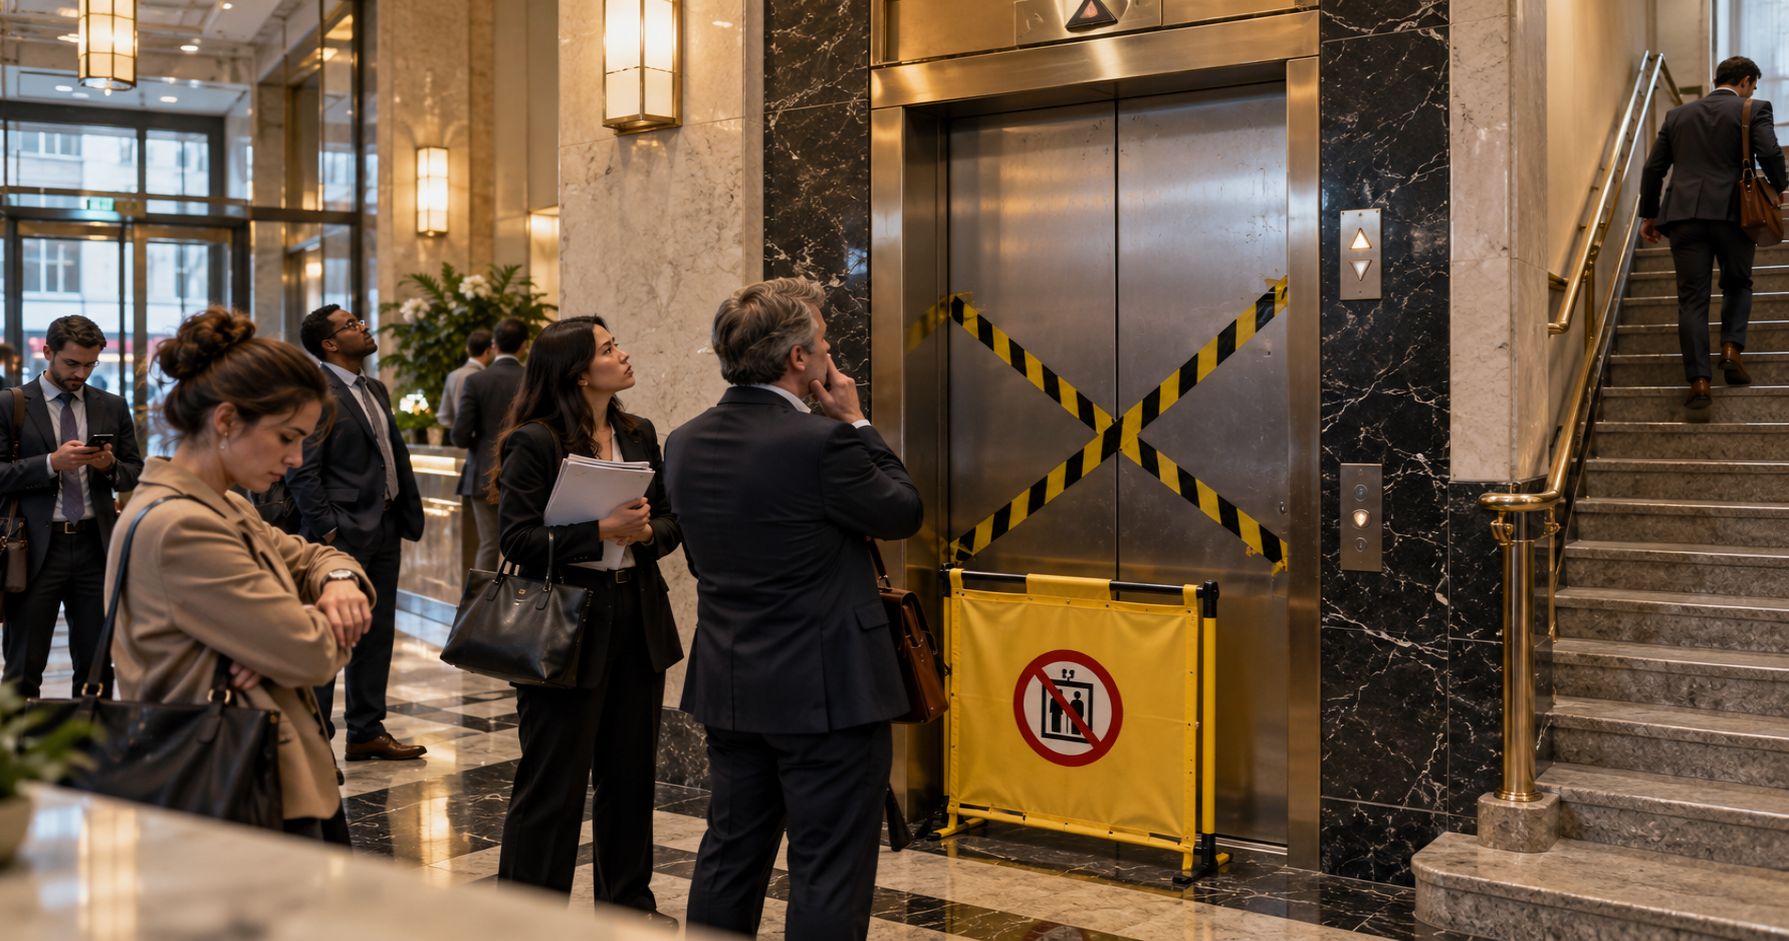
Then, a week after Labor Day in 2024, the building’s only elevator broke, and the owner couldn’t come up with the money for the part. It stayed broken for eleven weeks. Her team climbed nine flights every morning, and clients started suggesting the coffee shop on Lexington for meetings.
One of her senior designers, a guy with a bad knee, started working from home and never really came back. The heat didn’t come on until the week before Thanksgiving, either, and the space heaters kept tripping the breakers.
There Was No Cheap Way Out
She called me one morning that October from the stairwell, somewhere around the seventh floor. I could hear her breathing and the echo off the concrete before she said a word, and then she asked me how to get out of her lease.
I had to tell her she couldn’t, at least not cheaply. Her good guy guarantee would let her walk away personally once she gave notice and moved out, but the firm would still owe the rent. In New York, a landlord doesn’t have to re-rent the space to collect it. A buyout would have needed his lender’s sign-off, and a lender sitting on a shaky loan doesn’t let a paying tenant go cheap.
When she asked about a sublease, I asked her who she thought would climb nine flights to see the space. She was quiet for a second, and then she said, “So I’m stuck.” I told her she was, for eight more years, unless something gave first.
Ten Minutes to Vet Her Landlord
That night I sat down to vet her landlord, ten minutes of work that should have happened before she signed. I pulled the building up on ACRIS, the city’s free online property records, and found the 2019 mortgage. It was $38 million from a debt fund, and there was an extension recorded the year before she moved in.
Plenty of debt-fund loans come with extension options. But money was about as cheap in 2021 as it has ever been, so an owner who extended instead of refinancing was probably already struggling. The next morning, a couple of calls told me ownership was in trouble.
The Lender Took the Keys
Something gave about a year later, when the lender took the building and sold it to an owner with money. The next time the elevator broke, it was running again in nine days, and the lobby got its renovation that spring. She’s still there and likes the building again, but she brings up those eleven weeks every time we have dinner.
What bothers me most is that for two years her lease gave her no way to make a broke landlord do anything. If I’d been at the table when she negotiated the lease, I’d have pushed for rent abatement tied to the elevator and the heat, and those eleven weeks would have cost him instead of her.
The Next Wave Is on the Calendar
Her landlord got caught by a floating rate. The ones who get caught over the next couple of years will mostly be owners with fixed-rate loans from the cheap-money years, and those loans are coming due now. The Fed raised rates two weeks ago, its first hike since 2023. This week the 10-year Treasury, which lenders use to price commercial mortgages, passed 5.3% for the first time since 2002.
Even 245 Park, the tower from the Crain’s story, owes $1.768 billion at a fixed 4.30%, due next June. Banks are already putting together a bond deal to refinance it, and the new rate won’t be anywhere near 4.30%. That owner can handle it. Plenty of smaller owners can’t, and one firm that tracks recorded mortgages counts at least $5.9 billion in city commercial loans coming due within a year.
How to Vet Your Landlord Before You Sign
These days I look at the landlord before my clients fall in love with anything.
I start with the mortgage, because it tells you more about the next ten years than any tour will. I want to know how big the loan is compared to what the building is worth, when it comes due, whether the rate floats and who the lender is.
A bank loan running into the 2030s doesn’t worry me, but a debt-fund loan that’s been extended gets my attention. Then I look at who owns the building. A family that has owned buildings in this city for three generations can usually ride out a bad refinancing, and a single-building LLC with two partners often can’t.
Owners with money spend it where you can see it, so walk the whole building with an office tour checklist. If the lobby renovation is still a drawing on an easel, ask about it.
You Can’t Vet a Landlord From a Database
The public record only gets you about halfway when you vet your landlord. Many recorded mortgages don’t list a due date, and no website will tell you whether an owner is stretched thin. Beyond that, you’re relying on what people in the market hear and see.
Most leasing agents are decent, highly professional people, but they work for the landlord. The landlord pays my commission, too, but as a tenant rep broker, I have a professional and moral obligation to protect the tenants I represent and that’s why we try to take a landlord’s financial strength into account. At the very least, as much as that information is available.
Another thing I want to stress. At my firm, we’re not a credit rating agency. However, we do hear and see things. Major issues and red flags tend to come out, and when we know about one, we tell our clients. While the landlord goes through your tenant proposal package line by line, it helps to have someone in your corner.
Vet Your Landlord As He Vetted You
That’s the elevator she wanted me to tell you about. She read a draft of this, and her only complaint was that I made the stairs sound too easy.
Most landlords will get through the next couple of years without a problem. Some won’t, and their tenants will find out the way she did. Before you sign a ten-year lease, find out which kind of landlord you have.
If you’re looking at space in Midtown or Downtown this fall, call me before you send anybody your tax returns. I’ll look at the landlord and tell you if anything concerns me.